
3 Statement Real Company Modeling (Non-Cash Sweep)
Build a real-company three-statement model in which cash and debt balances follow explicit assumptions rather than an automatic cash sweep.
Model the company without an automatic debt sweep
A non-cash-sweep operating model separates the company forecast from automatic debt repayment. Participants learn how to spread real-company historicals, build assumptions and schedules, integrate the three statements, project cash and revolver balances, calculate interest, and test the finished model.
The session at a glance
Format · Live instructor-led webinar or in person Learning objectives · Spread a real company’s historical financials; develop forecast assumptions; build integrated income-statement, balance-sheet, cash-flow, and debt schedules; distinguish non-cash-sweep logic from cash-sweep logic; manage cash, revolver, and interest circularity; and test the completed model.
Live instruction. Build a real-company forecast without a cash sweep.
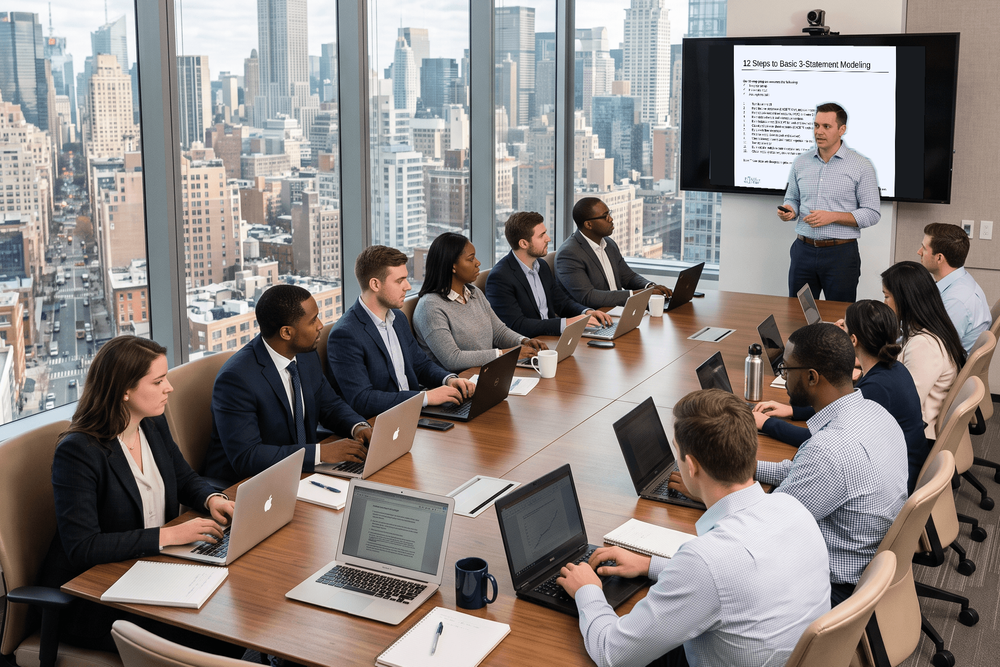
Using actual Pillars non-cash-sweep modeling materials, the instructor demonstrates the 12-step construction sequence and explains where debt, cash, revolver, and interest logic differs from a cash sweep. Participants connect public-company information to a stable integrated forecast.
Who this course is for
Designed for investment-banking, equity-research, corporate-finance, accounting, consulting, credit, and investing professionals, as well as students, who need to model a real company without assuming that all excess cash automatically repays debt.
How to prepare
Participants should understand the three financial statements and be comfortable with basic Excel formulas. Bring a recent annual report for a company you know and note how management describes revenue drivers, working capital, capital spending, debt, and liquidity.
Course agenda
Translate real-company disclosures into a forecast whose operating, cash, and financing logic remains explicit and reviewable.
Read the company and structure the workbook
Identify the relevant disclosures, organize source data, and establish the model architecture and conventions.
Spread historical financial statements
Build a consistent historical income statement, balance sheet, and cash flow statement from reported information.
Develop assumptions and supporting schedules
Forecast operating drivers, working capital, fixed assets, retained earnings, debt, and related calculations.
Integrate the projected statements
Build the forecast income statement, balance sheet, and cash flow statement and connect each schedule.
Model financing and validate outputs
Project cash, revolver, debt, and interest without an automatic sweep, then control circularity and verify balance, trends, and model integrity.
A certificate worth sharing
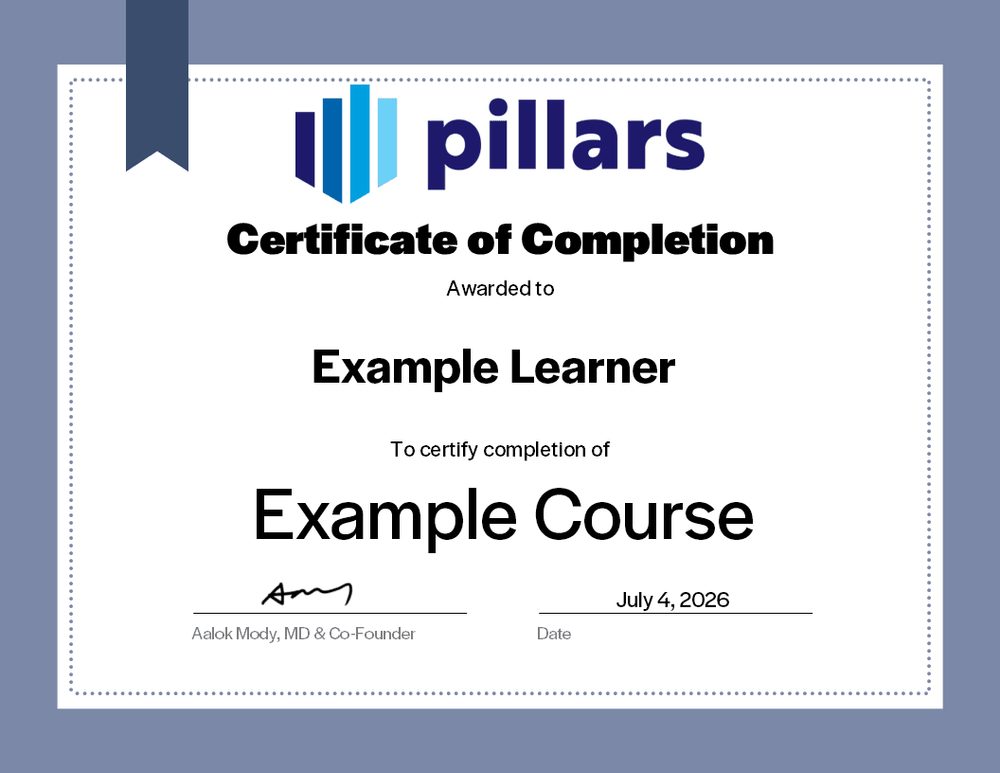
Upon completion, you will receive a certificate signifying your completion. Add it to your LinkedIn profile, résumé, or professional-development record.
Common questions
The practical details, in one place.
Is this live or on demand?
This is a live, instructor-led course delivered as a webinar or in person for a private business or school group.
What does the session cover?
The session covers real-company historical spreading, forecast assumptions, the three statements, supporting schedules, cash, revolver, debt, interest circularity, and model checks. It distinguishes non-cash-sweep modeling from models that automatically apply excess cash to debt repayment.
Are recordings, materials, or certificates included?
Live sessions include the materials used during the program and a certificate of completion. Recordings are not included unless explicitly arranged in advance.
I am a CPA, can this course offer CPE credit?
Yes. Eligible live sessions can be offered for CPE credit when the program is delivered and documented in accordance with Pillars’ CPE policies. Confirm the specific engagement details with Pillars before the session.
Bring real-company modeling to your team.
Give your team a disciplined method for turning company disclosures into an integrated forecast with explicit cash and financing assumptions.