
Greeks
Use delta, theta, gamma, vega, and rho to understand how option values and risks change.
Translate option sensitivities into practical risk insight
Overview · Outcomes · Audience · Agenda · Certificate · FAQ
The Greeks describe how an option’s value responds to changes in the underlying price, time, volatility, and interest rates. This live course turns delta, theta, gamma, vega, and rho into an applied framework for understanding option behavior, hedge exposure, and portfolio risk.
The session at a glance
Format · Live instructor-led webinar or in person Learning objectives · Explain delta, theta, gamma, vega, and rho, calculate or interpret each sensitivity, and evaluate how the Greeks change across option characteristics and market conditions.
Live instruction. Practical option risk.
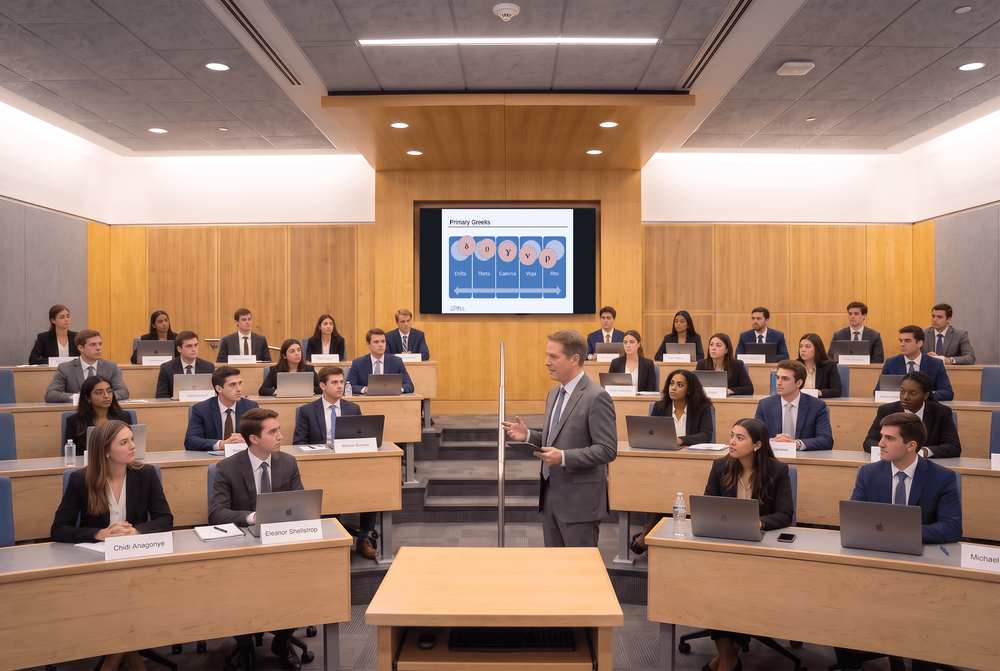
Work through calls, puts, and portfolio examples that show how each Greek changes as market inputs move. The instructor connects the sensitivities so participants can explain both first-order exposure and the risks created when that exposure changes.
Who this course is for
Designed for traders, risk professionals, sales and trading teams, investment professionals, and analysts who use or evaluate options and derivative exposures.
Preparation that makes the option analysis more useful
Bring an option position, market scenario, or risk question that you would like to interpret more clearly. Familiarity with basic call and put payoffs is helpful, but no advanced derivatives model is required before the session.
Course agenda
Build from individual sensitivities to a connected view of option and portfolio risk.
Establish what the Greeks measure
We begin by linking option value to the underlying price, time, volatility, and interest rates and by defining each primary sensitivity.
Interpret delta and hedge exposure
We compare call and put delta, use delta as an approximate hedge ratio, and examine how moneyness affects exposure.
Evaluate theta and time decay
We analyze how option value erodes over time and why the pace of decay changes as expiration approaches.
Understand gamma and changing delta
We examine curvature, identify positions with the greatest gamma exposure, and connect gamma to rebalancing needs.
Apply vega and rho in context
We close by evaluating volatility and interest-rate sensitivity and combining the Greeks to explain portfolio behavior.
A certificate worth sharing
Upon completion, you will receive a certificate signifying your completion. Add it to your LinkedIn profile, résumé, or professional-development record.
Common questions
The practical details, in one place.
Is this live or on demand?
This is a live, instructor-led course delivered as a webinar or in person for a private business or school group.
What does the session cover?
The session covers delta, theta, gamma, vega, and rho, including how each sensitivity changes across option characteristics and market conditions.
Are recordings, materials, or certificates included?
Live sessions include the materials used during the program and a certificate of completion. Recordings are not included unless explicitly arranged in advance.
I am a CPA, can this course offer CPE credit?
Yes. Eligible live sessions can be offered for CPE credit when the program is delivered and documented in accordance with Pillars’ CPE policies. Confirm the specific engagement details with Pillars before the session.
Bring practical options-risk training to your team.
Give your team a practical language for explaining option value, hedge exposure, and portfolio risk when market conditions change.