
Fixed Income
Analyze bond cash flows, prices, yields, duration, convexity, and the term structure of interest rates.
Connect fixed-income cash flows to price and risk
Overview · Outcomes · Audience · Agenda · Certificate · FAQ
Fixed-income analysis begins with promised cash flows and the rates used to discount them. This live course develops the relationship among bond structure, price, yield, spot and forward rates, duration, convexity, and yield-curve movements so participants can interpret value and interest-rate risk.
The session at a glance
Format · Live instructor-led webinar or in person
Learning objectives · Value common fixed-income cash flows; explain the inverse price-yield relationship; distinguish coupon, spot, forward, and par rates; calculate and interpret duration, convexity, and price sensitivity; and analyze the implications of yield-curve movements.
Live instruction. See how cash flows become price and risk.
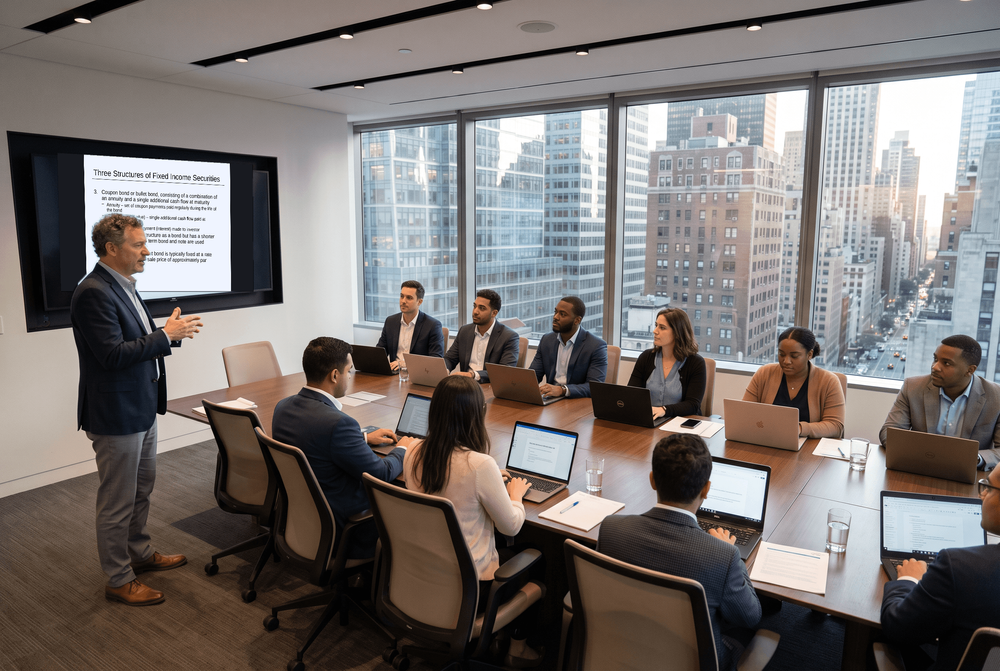
Work through actual Pillars fixed-income slides that break a coupon bond into its periodic interest and maturity payments. The instructor connects those cash flows to discounting, yield, the term structure, duration, convexity, and the way bond prices respond to changing rates.
Who this course is for
Designed for treasury, investment, banking, credit, accounting, corporate-finance, risk, and transaction professionals—as well as students—who need a rigorous but practical understanding of bonds and interest-rate exposure.
How to prepare
Bring a bond, yield-curve, or interest-rate-risk question you would like to analyze more clearly. Participants should be comfortable with basic present value and percentage calculations; a financial calculator or spreadsheet may be useful during examples.
Course agenda
Move from the contractual cash flows of a bond to valuation, yield measures, and the tools used to assess interest-rate risk.
Establish fixed-income cash-flow structures
Compare discount instruments, annuities, and coupon bonds and identify the timing of principal and interest payments.
Value bonds and interpret yield
Discount promised cash flows and explain the inverse relationship between a bond’s price and yield.
Build the term-structure framework
Distinguish spot, forward, par, and yield curves and connect them through no-arbitrage relationships.
Measure interest-rate sensitivity
Use duration, modified duration, PVBP, and convexity to estimate and interpret price changes.
Analyze yield-curve risk
Evaluate how parallel and nonparallel curve movements affect fixed-income securities and portfolios.
A certificate worth sharing
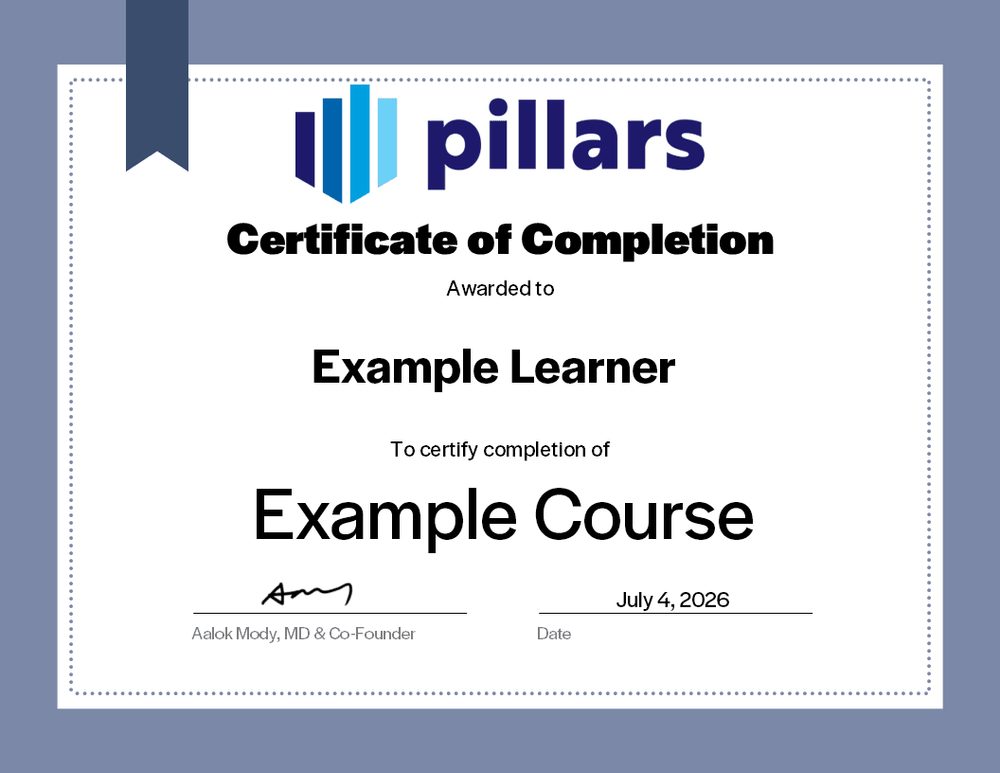
Upon completion, you will receive a certificate signifying your completion. Add it to your LinkedIn profile, résumé, or professional-development record.
Common questions
The practical details, in one place.
Is this live or on demand?
This is a live, instructor-led course delivered as a webinar or in person for a private business or school group.
What does the session cover?
The session covers fixed-income cash flows, bond pricing, yields, spot and forward rates, yield curves, duration, modified duration, PVBP, convexity, and interest-rate risk.
Are recordings, materials, or certificates included?
Live sessions include the materials used during the program and a certificate of completion. Recordings are not included unless explicitly arranged in advance.
I am a CPA, can this course offer CPE credit?
Yes. Eligible live sessions can be offered for CPE credit when the program is delivered and documented in accordance with Pillars’ CPE policies. Confirm the specific engagement details with Pillars before the session.
Bring practical fixed-income training to your team.
Give your team a stronger framework for valuing bonds, interpreting yields, and communicating interest-rate sensitivity.